Key Takeaways
MSCI’s simulated index deletions include Strategy, Metaplanet and Yellow Cake.JPMorgan estimated MSCI removal could trigger $2.8 billion in Strategy selling.Bitcoin Policy Institute says MSCI expects a decision by Oct. 16.
Wall Street’s Quiet Committee Can Move Billions
Your “passive” index fund isn’t quite as passive as the label suggests. Somewhere upstream, a private index provider writes the rules deciding which companies count as the market, and those decisions can send funds scrambling to buy or sell billions of dollars in shares.
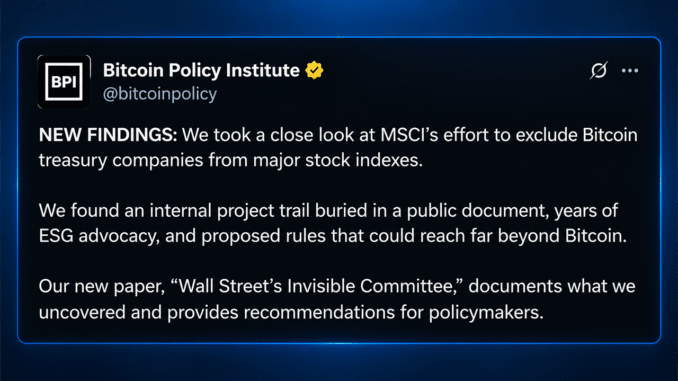
On Wednesday, the Washington, D.C.-based, non-partisan, non-profit think tank, Bitcoin Policy Institute, took the wraps off that machinery in a new paper by Executive Director Conner Brown, focusing on MSCI’s proposed test for “non-operating companies.” MSCI’s own simulation, according to the paper, would remove Strategy, Metaplanet, and Yellow Cake, a company holding physical uranium.
Passive Money Still Has Someone Picking the List
Brown’s paper on the subject puts some eye-popping numbers behind the power wielded by index providers. As of July, index funds held $21.8 trillion, or 53.9% of U.S. long-term fund assets, versus $18.6 trillion in actively managed funds. By 2025, index funds owned 19% of the U.S. stock market. MSCI alone says $21 trillion is benchmarked to its indexes, including $2.8 trillion in equity exchange-traded funds that track them directly.
That leads to one of the more counterintuitive points in Brown’s research. The index provider doesn’t actually manage those trillions. Fund managers do. Yet when an index provider changes the companies on its list, funds built to track that benchmark generally have to adjust with it. As Brown’s analysis lays it out, the firm writing the rulebook never touches the investor’s money, but its decisions can still set billions of dollars in motion.
The mechanics became considerably less theoretical in 2025. The Bitcoin Policy Institute author recounts how MSCI proposed excluding companies whose digital assets represented at least 50% of total assets, putting the bitcoin treasury firm Strategy squarely in the frame. JPMorgan analysts estimated Strategy’s removal could prompt roughly $2.8 billion in selling by MSCI-tracking funds, climbing to $8.8 billion if other index providers followed.
MSCI eventually nixed the proposal, but Brown points to what happened next. The firm froze increases in the number of shares it would count for affected companies and deferred new additions while preparing a broader review.
Bitcoin Rule Returns Wearing a Different Hat
Seven months later, Brown writes, MSCI came back with a broader test that no longer singled out bitcoin (BTC) or digital assets by name. Instead, the August proposal centers on whether a company has enough “operating assets.” A company failing the initial 50% screen faces five additional financial tests and, if it isn’t already an index constituent, can be excluded after triggering four of them. Existing constituents receive buffers and generally must fail during two consecutive annual reviews before removal.
Here’s where Brown sees a fundamental problem. His paper says “operating assets” isn’t a standardized balance-sheet category under U.S. GAAP or IFRS, leaving MSCI to classify everything from cash and mineral rights to unfinished construction, intellectual property and strategic holdings before the math can even begin.
Brown also zeroes in on Strategy’s bitcoin accounting. The company reported $22.8 billion in bitcoin-related operating losses during the first half of 2026, compared with $195 million in its other operating expenses. Count those figures as Strategy filed them, Brown argues, and one of MSCI’s flags wouldn’t be triggered. The 23-page paper contends that reaching MSCI’s simulated result, therefore, requires an analytical reclassification that the consultation doesn’t disclose.
The Uranium Twist Breaks the Story Wide Open
Brown’s argument gets considerably stranger once bitcoin leaves the picture. MSCI’s simulated deletions also include Yellow Cake, a company that holds physical uranium. The Bitcoin Policy Institute paper then takes the proposed methodology for a spin across other capital-intensive businesses, illustrating how the same logic might reach companies building satellites or a major U.S. lithium mine.
Under one plausible interpretation examined by Brown, AST Spacemobile could trigger four of MSCI’s flags and potentially be barred as a new index entrant. Lithium Americas presents an even sharper example. The company is building the Thacker Pass lithium project in Nevada, and Brown’s analysis finds it could also trigger four flags.
Lithium Americas reported $3.54 billion in assets in June, including $2.09 billion in mineral properties, plant and equipment. Yet Brown’s paper shows how a restrictive reading of MSCI’s proposal could make a mine still under construction look “non-operating” precisely because it’s expensive to build, hasn’t begun producing revenue and depends heavily on outside financing. The bigger the unfinished project, in other words, the stranger the accounting picture can become.
MSCI is expected to decide on or before Oct. 16, with any adopted changes slated for its November index review around Dec. 1. Brown’s paper starts with bitcoin treasury companies, but its argument ultimately lands somewhere much bigger. When trillions of dollars mechanically follow an index, the definition of what counts as an operating business is anything but academic.


Be the first to comment